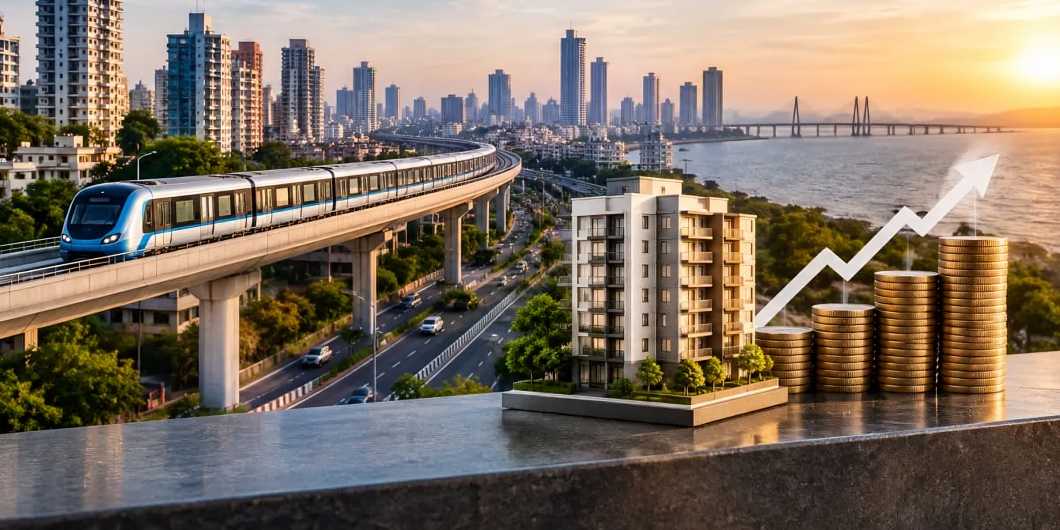


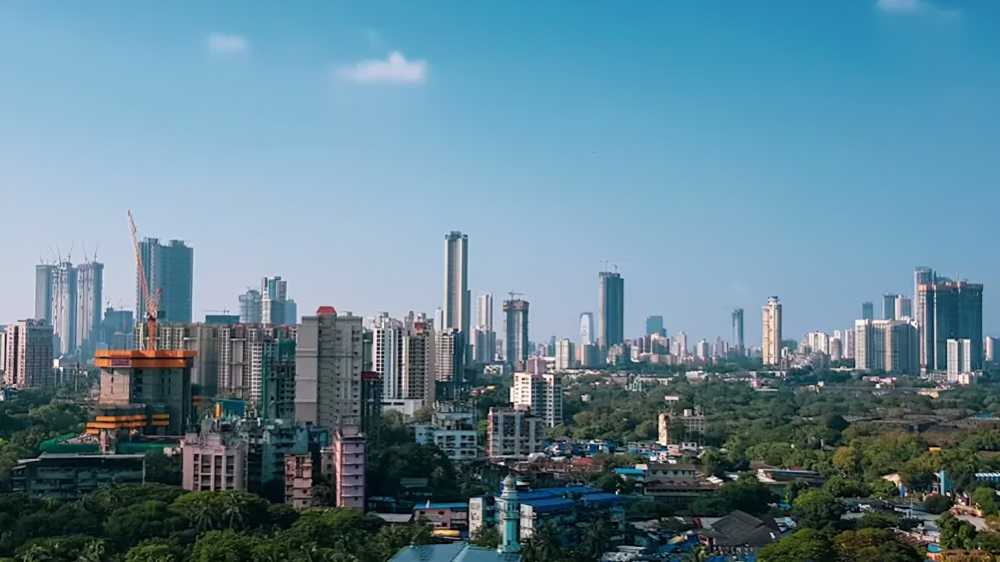
A Mumbai homeowner’s decision to sell a Rs 2 crore apartment in Dadar and invest the proceeds in a fixed deposit (FD) has triggered an online discussion about the financial merits of property ownership compared with bank deposits.
In a social media post, Ankit Pandey revealed that his relative had previously earned Rs 45,000 per month by renting out the apartment. The relative eventually sold the property, invested the money in an FD offering 6.5% annual interest and relocated to Borivali.
According to the post, the Rs 2 crore deposit could generate approximately Rs 13 lakh in annual interest before taxes, providing a regular income without the responsibilities associated with managing a rental property.
“No tenants. No maintenance headaches. Just regular income,” the post said.
The decision has renewed debate over whether property owners benefit more from rental earnings or by converting their real estate assets into financial investments. Renting out a home involves expenses and responsibilities, including society charges, repairs, tenant management and potential periods without occupants. These factors can reduce the actual returns from a property.
Selling the apartment and placing the proceeds in an FD offers a comparatively straightforward income stream. However, this approach also means giving up future rental earnings and the possibility of property value appreciation.
Fixed deposits generally provide predictable returns for a specified tenure, although interest income is taxable and renewal rates may change. Investors must also consider deposit protection. The Deposit Insurance and Credit Guarantee Corporation (DICGC) insures eligible deposits up to ₹5 lakh per depositor per bank, including principal and interest.
Real estate, meanwhile, can generate rent and appreciate over time, but involves maintenance expenses, property taxes and transaction costs. Rental returns can also fluctuate according to demand and occupancy.
Ultimately, choosing between an FD and a property depends on an investor’s financial goals, income requirements, liquidity needs and tolerance for risk. Comparing post-tax returns, ownership expenses and long-term growth potential is essential before making such a decision.
The case highlights that neither option is universally superior: the right choice depends on whether an investor prioritises predictable income, convenience or long-term wealth creation.
Source: NDTV Profit