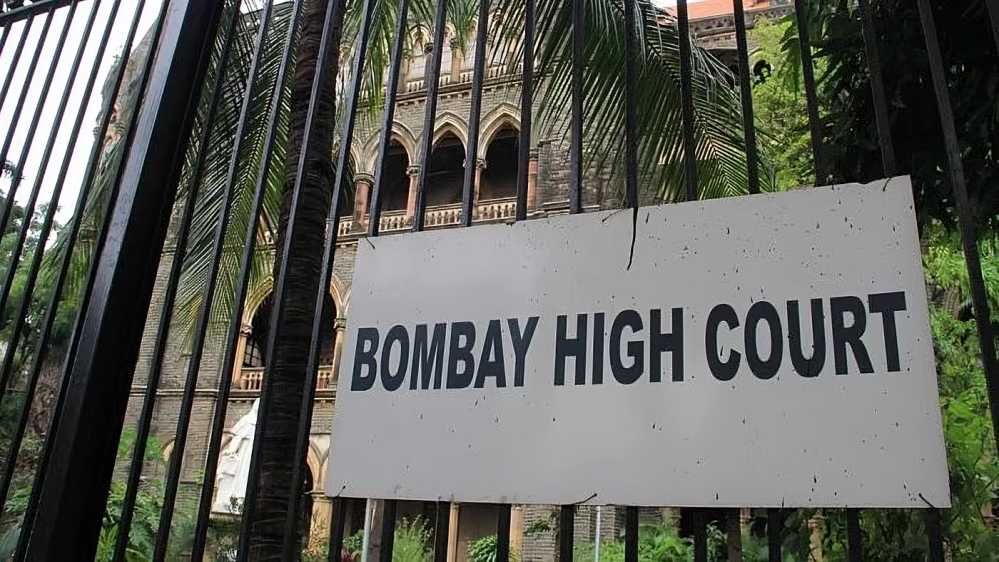


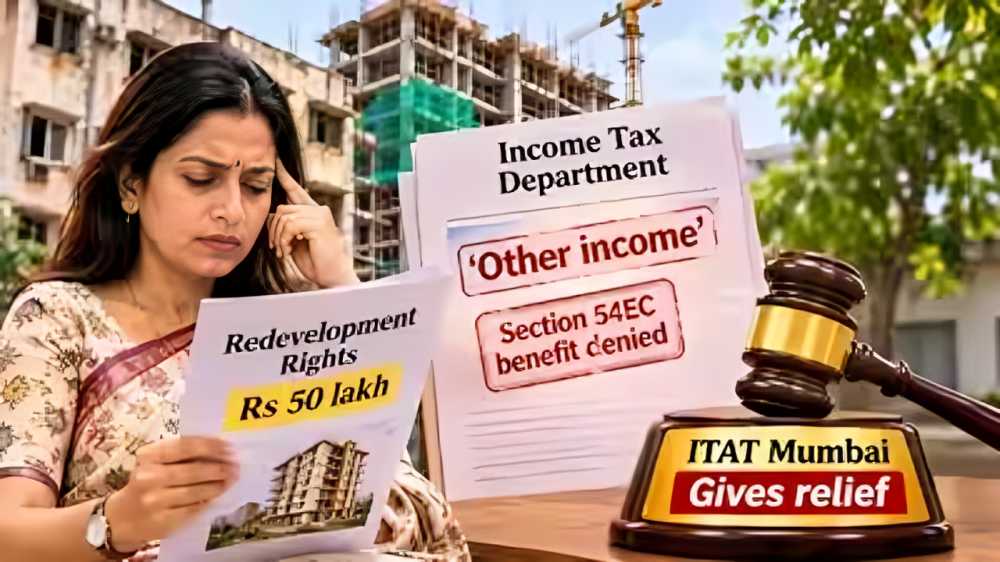
The Mumbai bench of the Income Tax Appellate Tribunal (ITAT) has ruled in favour of a property owner who received Rs 50 lakh from a developer under a redevelopment agreement, directing the Income Tax Department to treat the amount as capital gains instead of income from other sources. The decision also allows her claim for tax exemption under Section 54EC of the Income Tax Act, subject to verification of the prescribed conditions.
The woman had received Rs 50 lakh as her share of the monetary consideration under a redevelopment agreement signed on August 2, 2010. The arrangement involved 16 family members or property owners, four tenants and two additional claimants. Collectively, the owners were entitled to Rs 2 crore from the developer.
Under the agreement, the existing building was to be demolished and reconstructed. The owners retained floor space index (FSI) sufficient to construct 6,400 sq. ft. of residential carpet area, while the developer received the remaining development potential.
The taxpayer invested her Rs 50 lakh share in Rural Electrification Corporation (REC) bonds and claimed an exemption under Section 54EC in her income tax return for assessment year 2011-12. However, during reassessment proceedings initiated in 2018, the Assessing Officer classified the amount as income from other sources, denying the exemption. The Commissioner of Income Tax (Appeals) subsequently upheld the addition.
Why ITAT Reversed the Tax Department’s Decision
Challenging the assessment, the woman argued that the payment represented consideration for transferring valuable development rights, which qualified as a capital asset.
The tribunal agreed, observing that development rights attached to immovable property constitute valuable capital assets. It clarified that transferring such rights can amount to a capital asset transfer even when the owners retain ownership of the underlying land or building.
The order stated: “The consideration was therefore intrinsically connected with the rights parted with by the assessee and other owners in favour of the developer.”
The tribunal further observed: “However, from this finding, it does not follow that there was no transfer of any capital asset at all.”
It also rejected the argument that the developer’s accounting treatment should determine the tax classification, stating: “The taxability of a receipt in the hands of the recipient has to be determined with reference to the nature of the right transferred by the recipient and not on the basis of the accounting treatment adopted by the payer.”
During the appeal, the taxpayer passed away in early 2026, following which her daughter was substituted as the legal representative.
The ITAT directed the Assessing Officer to assess the Rs 50 lakh under capital gains and allow the Section 54EC exemption after verifying compliance with statutory requirements, including investment timelines and the prescribed bond lock-in period.
Source: Times of India